 Call us now:
Commercial vehicles need a different appraisal approach because they depreciate, get used, and get valued differently than personal vehicles. A standard passenger-car valuation method misses most of what actually drives their worth. Take a pickup truck logging 40,000 miles a year for a landscaping company, next to a personal commuter car with the same mileage. Once you factor in usage, maintenance history, and resale market, the two have almost nothing in common.
TL;DR: Commercial vehicles require an appraisal approach built around business usage, not personal-vehicle depreciation curves. Assessing a business’s vehicles as a group adds another layer, since their combined value often depends on how they work together, not just on their own. If your business owns commercial vehicles, our commercial appraisal service reflects this approach directly.
What Counts as a Commercial Vehicle?
A commercial vehicle is any vehicle used mainly for business rather than personal use. That ranges from a single work truck to a full delivery fleet. It also covers a landscaping trailer setup or specialized equipment like a bucket truck or refrigerated van. Ownership structure, usage pattern, and registration type all factor into whether a given vehicle counts.
The category is broader than most owners expect. A personally titled pickup used daily for a contracting business can qualify as a commercial vehicle for appraisal purposes. It doesn’t need a commercial registration to count. Usage and business purpose matter more than the title itself when it comes to how someone should actually value the vehicle.
How a Commercial Vehicle Appraisal Differs From a Standard Passenger Vehicle Appraisal
Usage intensity, upfit equipment, and business-specific wear separate a commercial vehicle appraisal from a standard passenger vehicle appraisal. Passenger car appraisals assume fairly predictable, personal-use mileage and condition. That assumption doesn’t hold once a vehicle sits in daily commercial service.
Upfit equipment alone changes the calculation a lot. Picture a work van with a custom shelving and ladder rack system, or a truck with a specialized lift gate. That equipment carries real value. A standard vehicle valuation tool has no way to account for it, since those tools only cover factory-standard passenger and light-duty vehicles.
Why Fleet Evaluation Requires Looking at More Than One Vehicle at a Time
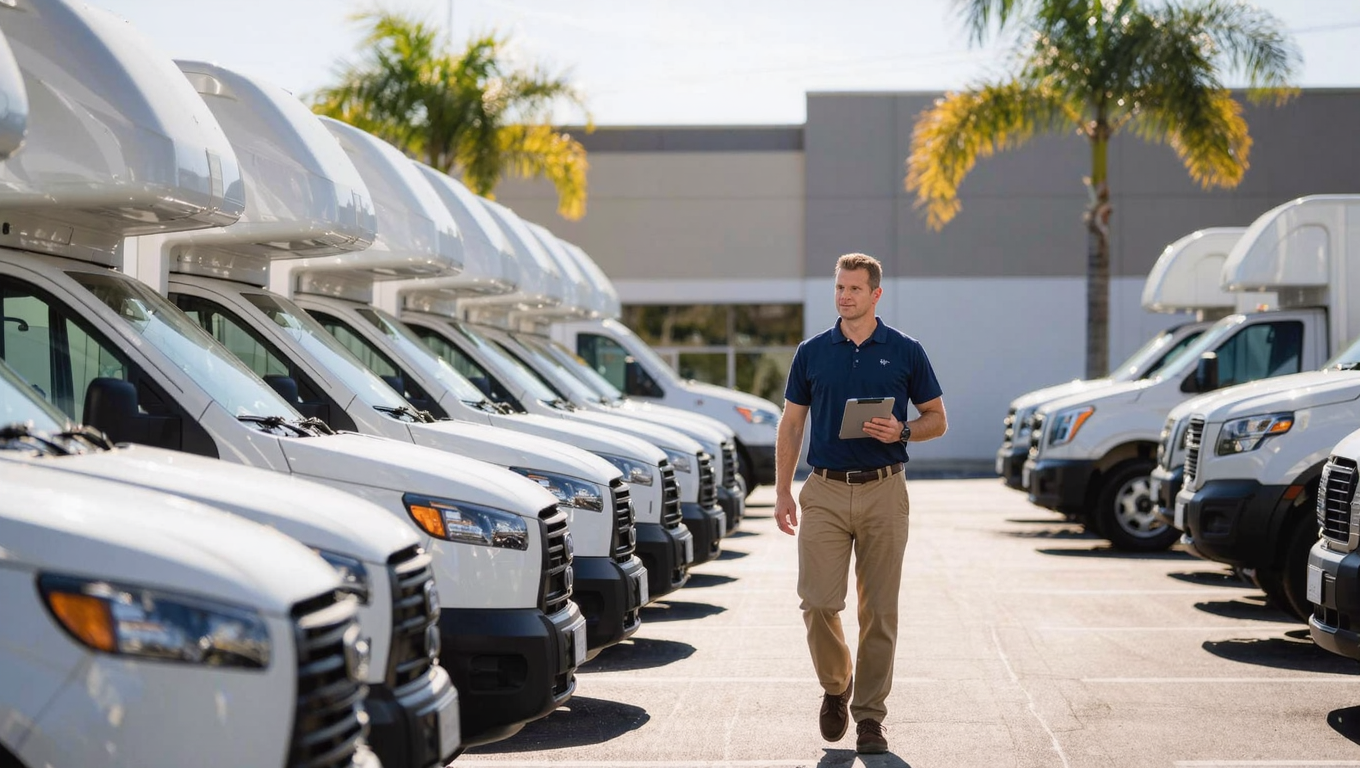
Fleet evaluation means assessing vehicles as a group. A fleet’s overall value, and its risk profile, often depends on relationships between vehicles that an individual appraisal would miss entirely. Consistent maintenance patterns, staggered replacement cycles, and how uniformly the fleet was actually used all matter here.
Pull a single company van from a fleet of twenty and appraise it in isolation, and it might look fine. That inspection alone, though, says nothing about whether the other nineteen vehicles share the same maintenance gaps or usage intensity. Fleet evaluation samples across the whole group instead, looking for patterns a one-off inspection can’t surface. That’s why financing, insurance, and resale decisions involving multiple vehicles usually call for a fleet-level review, not a series of disconnected single-vehicle appraisals.
How Usage, Mileage, and Wear Drive Commercial Vehicle Depreciation
Usage intensity and duty cycle mainly drive commercial vehicle depreciation, not just mileage on the odometer. A vehicle driven hard on short, stop-and-go routes wears differently than one covering the same mileage on highway routes. That distinction matters more for commercial vehicles than it typically does for personal ones.
Duty cycle, load weight carried regularly, and idle time also factor into how a commercial vehicle depreciates. Consider a box truck that spends hours idling with a refrigeration unit running. It builds up engine hours far beyond what its mileage alone would suggest, and a valuation that only looks at mileage will consistently overstate that vehicle’s remaining useful life and resale value.
What a Business Vehicle Appraisal Report Needs to Include
A business vehicle appraisal report needs to document usage history, upfit equipment and its condition, and maintenance records specific to commercial duty cycles. It also needs comparable sales data drawn from the commercial vehicle market, not the personal vehicle market. Missing any of these elements weakens the report’s usefulness for financing, insurance, or resale decisions.
Maintenance documentation carries real weight here. Commercial vehicles are more likely to have detailed service records tied to fleet management software. Those records can either support or undercut a valuation, depending on what they show. Our breakdown of what belongs in a certified appraisal report covers the documentation standard this builds on.
When Fleet Owners Need an Appraisal: Financing, Resale, Insurance, and Tax Planning
Fleet owners typically need an appraisal for financing decisions, pre-sale valuation, insurance coverage adjustments, or tax planning around depreciation and asset value. Each of these situations calls for a documented valuation rather than an internal estimate. A lender, insurer, or tax authority will each want to see the reasoning behind the number.
Financing situations especially depend on an accurate, documented valuation, since a lender’s assessment of collateral value directly affects loan terms. Our breakdown of how actual cash value appraisals help financial institutions covers how this works in practice, including why a financial institution generally wants independent documentation rather than the fleet owner’s own estimate.
Why an Independent Appraisal Matters More for Commercial Vehicles
An independent appraisal matters more for commercial vehicles because the stakes attached to the number are typically higher. Financing terms, insurance premiums, tax positions, and multi-vehicle sale deals all hinge on that figure. It needs to hold up under scrutiny from a bank, an insurer, or a tax authority.
A fleet owner has an obvious interest in the valuation landing a certain way depending on the purpose: higher for financing collateral, lower for tax depreciation planning. That’s exactly why an independent appraisal carries more weight than an internal estimate the business produces itself. The independence removes the question of whose interest the number serves.
Get a Commercial Vehicle Appraisal
Whether it’s a single work truck or a full fleet, Auto Praise can provide an independent, documented valuation built around your business’s actual usage and duty cycle, not a generic passenger-vehicle formula.
How Auto Praise Approaches Commercial Vehicle Appraisals
When we appraise a commercial vehicle or fleet, we start by establishing the actual usage pattern and duty cycle rather than assuming standard depreciation, since that’s the single biggest factor a generic valuation tool gets wrong on business vehicles.
From there, we document upfit equipment separately from the base vehicle, source comparable sales from the commercial market specifically, and build the report to whatever purpose it needs to serve, whether that’s financing, insurance, resale, or tax planning. That documentation-first process is what makes the resulting valuation usable well beyond a single conversation with one lender or insurer.
Fleet and commercial vehicles carry value in places a standard passenger vehicle valuation was never built to look: usage intensity, upfit equipment, and duty cycle all shape a commercial vehicle’s real worth. An appraisal built around those factors, rather than a personal-vehicle depreciation curve, is what actually holds up when financing, insurance, or a sale depends on the number.
Frequently Asked Questions
How often should a business get its fleet appraised?
Many businesses appraise fleet vehicles annually or when a specific need arises, such as refinancing, insurance renewal, or a planned sale. More frequent appraisals make sense for fleets with high usage intensity or rapid depreciation.
Does a commercial vehicle appraisal cost more than a personal vehicle appraisal?
It can, since commercial appraisals typically involve more documentation, upfit evaluation, and usage analysis than a standard passenger vehicle appraisal. Cost also scales with the number of vehicles involved when a business’s whole fleet is being assessed together.
Can a personally owned vehicle used for business still need a commercial appraisal approach?
Yes. Usage and business purpose matter more than titling or registration classification, so a personally titled work truck used primarily for business should still be appraised using commercial methodology.
What upfit equipment gets factored into a business vehicle appraisal?
Common examples include shelving and racking systems, lift gates, refrigeration units, tow packages, and specialized tool storage. Each is valued separately from the base vehicle since it affects both function and resale value.
Does high mileage always mean lower value on a commercial vehicle?
Not necessarily to the same degree it would on a personal vehicle. Duty cycle, maintenance history, and how the mileage was accumulated often matter more than the raw number for commercial vehicle valuation.
Can an independent appraisal support an insurance claim after an accident on a commercial vehicle?
Yes. A documented, independent valuation supports both diminished value and total loss claims on commercial vehicles the same way it does for personal vehicles, though the comparable data and usage factors differ.
Is a fleet evaluation different from appraising each vehicle separately?
Yes. Assessing the vehicles together looks for patterns across the group, such as consistent maintenance gaps or usage intensity, that a series of individual appraisals wouldn’t necessarily surface on their own.