 Call us now:
Appraisal clause insurance language is a provision built into most auto policies that gives either the policyholder or the insurer the right to demand an independent appraisal when they disagree on the amount of a loss. It’s not a lawsuit, it’s not arbitration, and it isn’t limited to total loss disputes, though that’s the context most owners hear about it in.
TL;DR: Appraisal clause insurance language applies any time you and your insurer disagree on the dollar amount of a covered loss, whether that’s a total loss valuation, or a disputed repair estimate. If you’re specifically ready to invoke it after a total loss, our step-by-step guide to invoking the total loss appraisal clause walks through that process directly.
What Is an Appraisal Clause in an Auto Insurance Policy?
An appraisal clause is a contract provision that lets either party to a policy demand an independent, structured process for resolving a disagreement over the dollar amount of a loss, separate from filing a lawsuit. Each side selects its own appraiser, and if those two appraisers can’t agree, they select a neutral umpire to break the tie. The resulting decision is typically binding on the amount of loss.
The clause exists because insurance contracts need some mechanism for resolving value disagreements that doesn’t require litigation every time two sides see a number differently. Appraisal clause insurance language shows up in the policy itself, usually in the conditions section, and it applies the moment there’s a genuine disagreement on amount, not fault or coverage.
Understanding Your Right to Appraisal as a Policyholder
Your right to appraisal exists independently of whether the insurer mentions it. It’s written into the policy contract you already have, and invoking it doesn’t require retaining an attorney or filing anything in court. Either party, you or the insurer, can invoke the clause once there’s a genuine dispute over the amount of loss.
Some policyholders hesitate to exercise their right to appraisal because they assume it’s a legal process reserved for serious disputes. In practice, it’s a documented, structured negotiation tool built directly into the contract, and using it is more straightforward than most owners expect once they understand it’s a right they already have, not a request they need to ask permission for.
Appraisal Clause Insurance Language: Where It’s Found and How It’s Worded
Appraisal clause insurance language typically appears in the “Conditions” or “Loss Conditions” section of an auto policy, usually as a short paragraph outlining the process: each party names a competent and disinterested appraiser, the appraisers set the amount of loss, and if they disagree, an umpire selected by both appraisers resolves the difference.
The wording rarely singles out total loss specifically. Most policy language refers broadly to disagreement on “the amount of loss,” which is exactly why the clause covers more ground than most owners assume. Reading your own policy’s specific wording matters here, since the exact process and any deadlines can vary slightly by insurer, even though the underlying structure is fairly consistent across the industry.
Can You Fight a Total Loss Claim Using an Appraisal Clause?
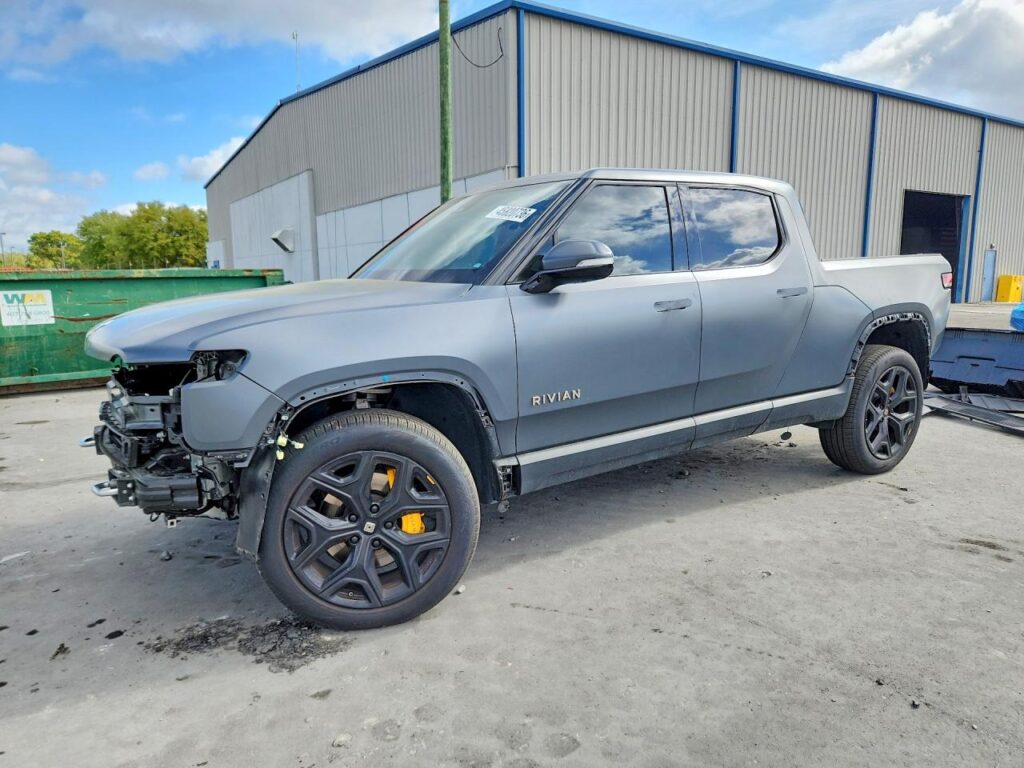
Yes, you can fight a total loss claim using an appraisal clause when you disagree with the insurer’s actual cash value figure. This is the most common context the clause gets discussed in, and it remains one of the strongest tools available to a Florida policyholder who believes a total loss settlement is undervalued.
The honest answer to “can you fight a total loss claim” this way is yes, but success often comes down to the strength of the valuation your own appraiser brings to the process, not just the fact that you invoked the clause. If you’re specifically at this stage, disputing a total loss number rather than trying to understand the clause itself, our dedicated guides cover that ground in more depth: challenging your insurer’s total loss offer and Florida’s total loss law both walk through the total-loss-specific mechanics this article intentionally doesn’t repeat.
Get a Total Loss Appraisal Review
If you believe your insurer’s total loss offer may not accurately reflect your vehicle’s value, Auto Praise can provide an independent review and valuation consultation before you accept a settlement.
How the Appraisal Clause Applies Across Claim Types
| Claim Type | What’s Disputed | Where to Go Deeper |
| Total loss | Actual cash value of the vehicle | Invoking the total loss appraisal clause |
| Disputed repair estimate | Cost of repair itself | Covered generally under the same policy language, case-specific documentation applies |
How Auto Praise Supports Florida Vehicle Owners Through the Appraisal Process
When a Florida policyholder is deciding whether the appraisal clause fits their situation, our role starts before anyone invokes anything: documenting the vehicle’s actual condition and value independently, so whichever appraiser ends up representing that side of the process has a defensible, comparable-sales-based number to work from rather than a desk estimate.
That documentation matters the same way whether the underlying dispute is a total loss valuation, since the appraisal clause process itself doesn’t change based on claim type, only the number being contested does.
Appraisal clause insurance language exists to resolve one specific kind of disagreement, the dollar amount of a covered loss, without requiring a lawsuit to get there. It applies to total loss disputes, and disputed repair estimates alike, which is the part most owners never hear until they’re already mid-dispute.
Frequently Asked Questions
Do I need a lawyer to invoke the appraisal clause?
No. Invoking the appraisal clause is a contractual right built into the policy, separate from litigation, and it doesn’t require retaining an attorney to get started. Legal counsel becomes more relevant if the dispute escalates beyond the appraisal process itself.
What happens if the two appraisers can’t agree?
The policy typically calls for the two appraisers to select a neutral umpire, who then resolves the specific point of disagreement. This umpire step is where many disputes actually get decided, since it’s rare for both sides’ appraisers to agree immediately.
Is the appraisal clause result legally binding?
Generally, yes, on the amount of loss specifically. It typically doesn’t resolve broader coverage disputes, only the dollar figure in question, which is an important distinction if other issues are also contested in the claim.
Can an insurer refuse to honor the appraisal clause?
Generally not, since the clause is part of the contract both parties agreed to. An insurer can dispute specific aspects of how the process is being invoked, but outright refusing a properly invoked appraisal clause is not typically consistent with the policy’s own terms.
Does invoking the appraisal clause cost anything?
Each party is typically responsible for its own appraiser’s fees, with umpire costs often split evenly. This is worth weighing against the size of the disputed amount before deciding whether invoking the clause makes sense for a particular claim.
Is there a time limit for invoking the appraisal clause?
Some policies include specific windows or notice requirements for invoking the clause, so reviewing your own policy’s exact wording matters. Waiting too long after a dispute arises can complicate the process even where no strict deadline is stated.
Can the appraisal clause be used more than once on the same claim?
Typically, no, once an appraisal award is issued on a specific disputed amount, it generally resolves that question, though a genuinely separate dispute arising later in the same claim could potentially trigger the clause again.